Asset Allocation for Beginners Planning Guide
This content applies specifically to South Korea.
If you need savings for tuition or a home payment, separate that money and essential living costs before deciding how much to invest. Base the investment amount on when the remaining savings will be needed and how much loss is bearable. This keeps planned spending central to the decision.
Match the investment to the spending date
Asset allocation means spreading money across assets such as stocks and bonds. Start with spending dates and an emergency reserve sized around essential expenses and income stability. With loans, compare interest saved through repayment against expected investment returns after tax, including any early repayment fee.
Product labels alone cannot tell you whether money will be available when needed. An ETF is a fund traded like a stock; interest rate ETFs can lose principal. A TDF adjusts its mix of assets around a target date, but can also lose money. Check withdrawal terms alongside risk.
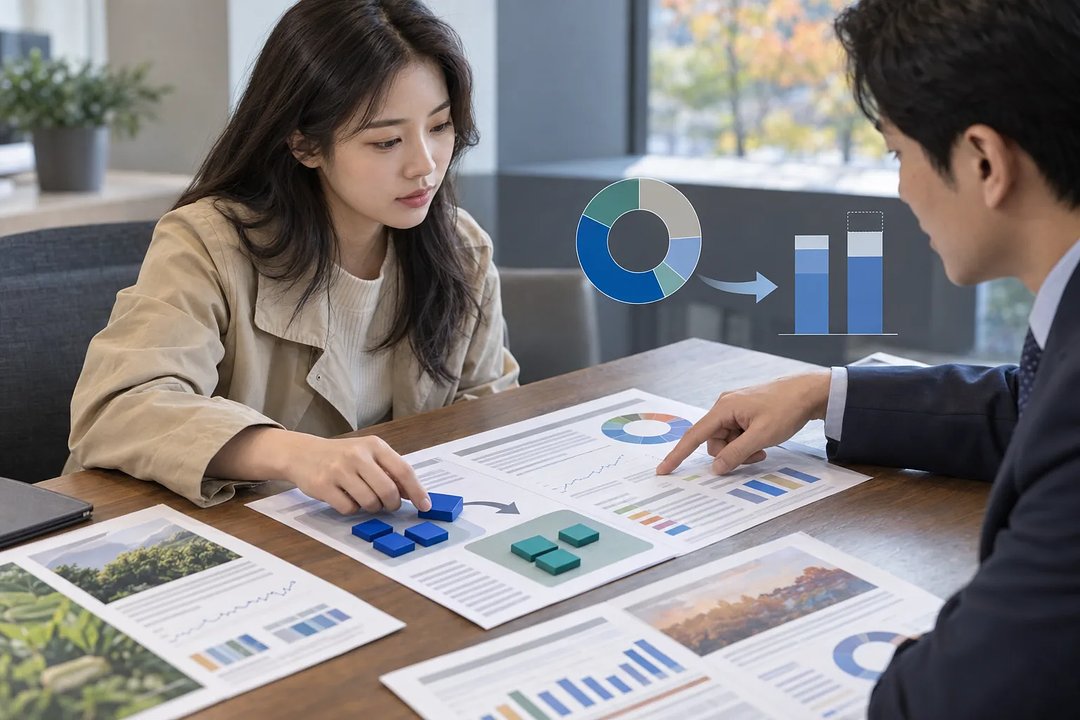
Use the asset allocation comparisons
The original article on Injoys gives you product comparison tables, allocation examples and checks for costs and access to cash. Its useful distinction between an account and the investment held inside it helps explain why funding a pension account does not automatically buy a TDF.
Read the full article on Injoys
A spending-date checklist
Before choosing a product, you can turn the guidance into a short decision checklist:
- For tuition or a home payment, write down the payment date and check when cash can be withdrawn.
- For regular salary savings, identify the amount that can consistently be set aside; consider regular investing only for long-term funds.
- For retirement money, compare the TDF target year with the expected spending date and check its current stock allocation.
Check which examples fit the situation
The sample portfolio is an illustration, not a recommended mix for every beginner. Its stock exposure reaches 65% when dividend stocks are included. More product names do not necessarily mean less overlap.
If you are considering the Korean pension accounts discussed, check account-specific conditions first. Some early withdrawals from an IRP, a retirement account, are limited to reasons set by law. Ask the account provider about withdrawal and closure taxes.
You could start today by writing down planned expenses and their payment dates, then use those dates to compare withdrawal terms.
Read the full article on Injoys
This post was written with assistance and published on a channel run by Injoys (injoys.com). The original article and its sources are at the link above.


Comments
Post a Comment