Pension Savings ₩500,000 Monthly Tax Credit Guide
This content applies specifically to South Korea.
If you can set aside ₩500,000 a month, pension savings alone can reach the ₩6 million annual contribution limit eligible for a tax credit. Extra IRP contributions need a separate budget. The credit reduces tax owed, so the calculated amount is not a guaranteed refund.
Match contributions to available money
Keep emergency funds and money needed soon separate so everyday bills do not require borrowing to maintain pension contributions. The ₩500,000 monthly amount is an example; you can start with less.
At ₩750,000 a month, the article's example puts ₩500,000 into pension savings and ₩250,000 into an IRP, an individual retirement pension account. That reaches the combined annual contribution limit of ₩9 million eligible for a tax credit.
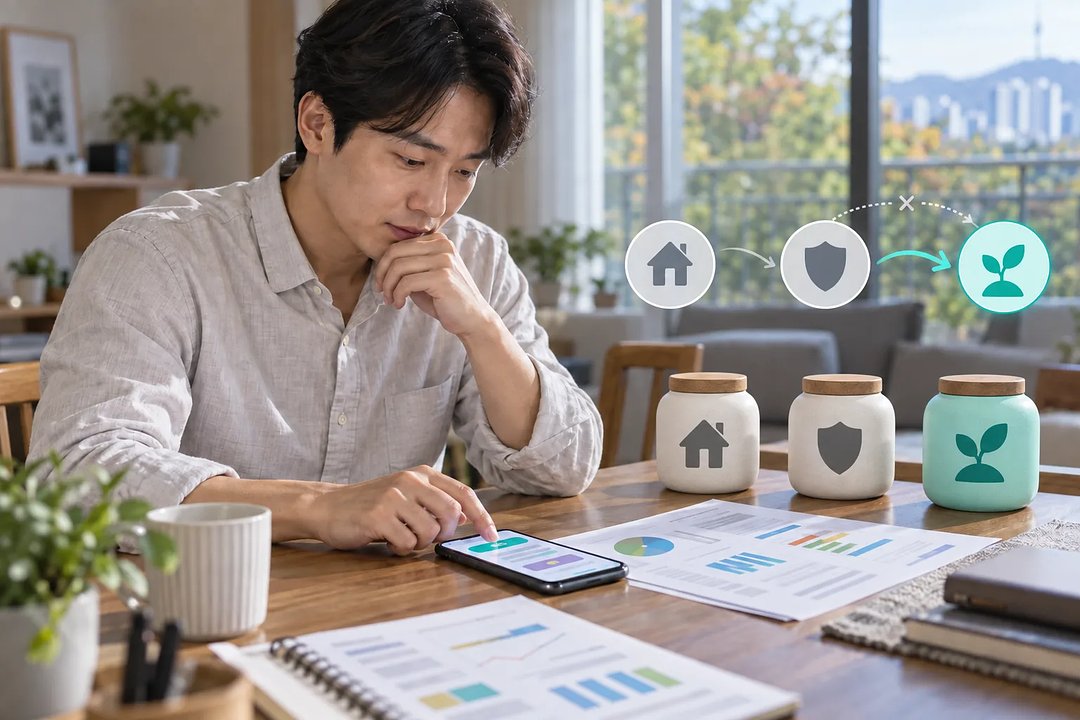
Pension savings and IRP compared
For account choices, you can use the comparison tables in the original article on Injoys to assess withdrawal restrictions, investment limits and fees. Its income-based credit table and transfer checklist help connect the saving target to the tax calculation and actual investment purchases.
Read the full article on Injoys
Connect a monthly budget to a tax credit
Suppose you have employment income only, total salary of at most ₩55 million for the relevant tax year, and contribute ₩500,000 monthly to pension savings. The annual ₩6 million contribution gives a calculated tax reduction of ₩990,000 at 16.5%, including local income tax, under the tax figures based on the Income Tax Act effective July 1, 2026.
Treat those figures as different parts of the plan: ₩6 million is money contributed, while ₩990,000 is the calculated tax reduction. Insufficient tax liability can limit the credit received. Total salary also differs from take-home pay.
Check account eligibility and access
Pension savings is available even without income. For an IRP, you need to check legal eligibility, such as being an employee or self-employed. Partial early IRP withdrawals are restricted to reasons specified by law; pension savings permits partial withdrawals, but taxation depends on the source of the money withdrawn.
A useful first step is to check the estimated pension benefit with the National Pension Service, then compare it with expected retirement living expenses before choosing a contribution.
Read the full article on Injoys
This post was written with assistance and published on a channel run by Injoys (injoys.com). The original article and its sources are at the link above.


Comments
Post a Comment