Storm, Flood, and Earthquake Insurance Tenant Claim Steps
AI-generated image
This content applies specifically to South Korea.
Facing flooded furniture in a rented home? If you insured only household contents, that policy does not cover building repairs. The claim limitation period is generally 2 years, but damage must be reported and the site preserved immediately; waiting makes the loss harder to verify.
Match the damage to the insured property
Check what your policy lists: an owner-occupied home's building, a tenant's household contents, or a small business's commercial or factory property. A shared address does not mean shared coverage. This distinction helps you identify which policy to check before gathering claim documents.
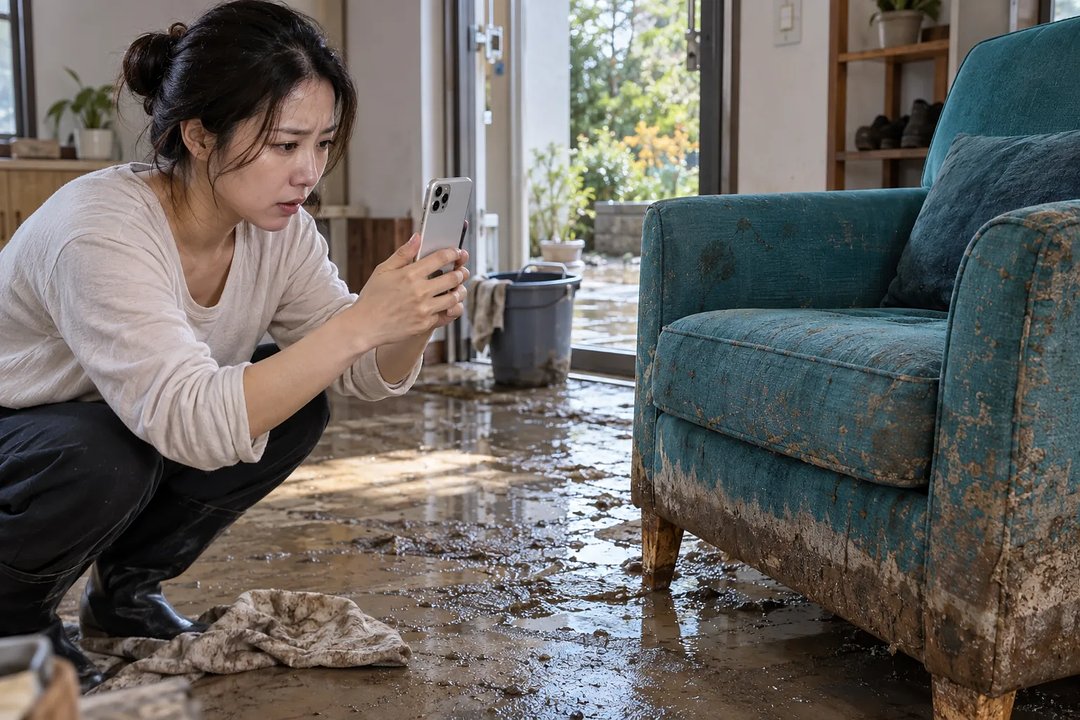
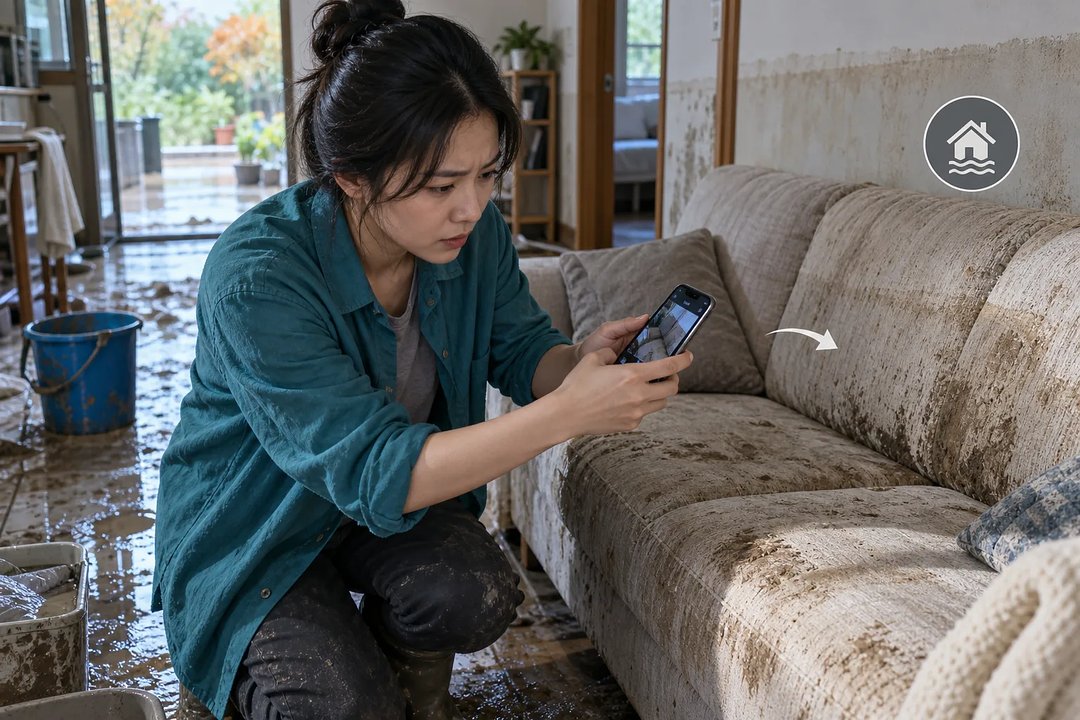
Prioritize safety: enter only after the flooded area is confirmed safe. Then photograph rooms, water levels and individual damaged items, and report the incident immediately. Keeping records before cleanup leaves less to reconstruct while arranging repairs.
AI-generated image
Flood insurance guidance worth keeping nearby
Use the original article on OnBinder for its claim sequence, evidence checklist and comparison with fire insurance and disaster assistance. Its practical strength is connecting each damaged item to the relevant policy, while explaining what to confirm before disposal or major repairs.
Read the full article on OnBinder
A quick check for a flooded rental
- Separate the losses: wet furniture and damaged walls require different coverage checks. Where both parties' property is damaged, report separately under each party's policy.
- Record before clearing: photograph damaged items and list quantities. Obtain the insurer's confirmation before disposal ahead of the investigation.
- Keep the paperwork: retain emergency drainage and temporary mitigation receipts, then ask which claim documents are required.
Check eligibility and the coverage start date
Before enrolling, you need to check ownership or tenancy rights and the building's use. Small businesses require eligibility checks; agricultural greenhouses must meet officially announced specifications. Differences between actual use or structure and official records require additional verification.
Enrollment must precede the disaster. Paying a premium does not establish that coverage has started, and enrollment may be restricted after a weather advisory or warning or when disaster is imminent.
Already affected? Contact your insurer now with the policyholder details, incident date and time, address and cause of damage. Use the original article on OnBinder to prepare the supporting evidence.
Read the full article on OnBinder
This post was written with assistance and published on a channel run by OnBinder (onbinder.com). The original article and its sources are at the link above.


Comments
Post a Comment